Industrial cost increases heighten global inflation risks amid rising metal prices
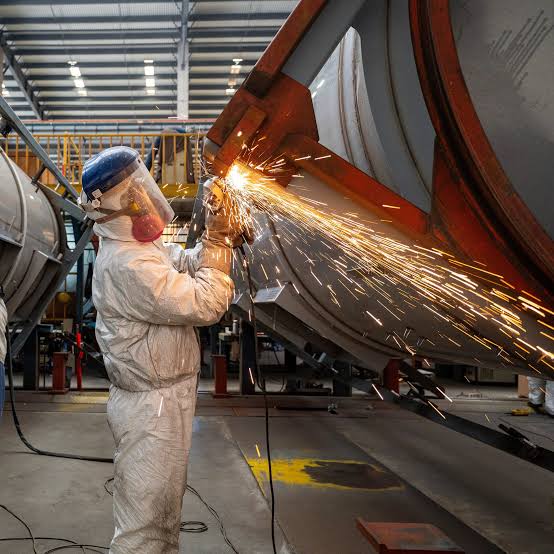
Islamabad , Nov 13,2026: Rising prices of metals and other industrial inputs are creating additional inflation risks across major economies, with higher manufacturing costs potentially feeding into consumer prices even as energy remains a major driver of inflation.
Producer-price data from the United States, China and the United Kingdom indicate that cost pressures are extending across manufacturing supply chains, raising concerns that businesses could face higher expenses before their full impact becomes visible in headline inflation.
In the United States, the Producer Price Index for final demand rose 1.3% in September, its largest monthly increase since March 2022, while the index increased 6.3% year on year, according to the Bureau of Labor Statistics.
Final-demand goods prices increased 2.6% during the month, while prices for unprocessed goods used as intermediate inputs jumped 8.4%. Unprocessed non-food materials excluding energy rose 2.5%, with increases also reported in fabricated structural metal products and nonferrous metal ores.
Dr Uzma Zia, Senior Research Economist at the Pakistan Institute of Development Economics, told Wealth Pakistan that metal-price shocks could be harder to identify than energy shocks because their effects often emerged gradually through manufacturing and production costs.
“Metals are embedded in machinery, construction, vehicles, electrical equipment and industrial components. When these prices rise, the impact may initially remain inside company cost structures before appearing in final goods prices,” she said.
She explained that the extent of the inflationary impact would depend on how long higher input costs persisted and how much pricing power manufacturers retained.
China’s producer-price data also indicate rising industrial cost pressures.
According to the National Bureau of Statistics, industrial producer prices increased 5.0% year on year in September, while purchasing prices paid by industrial producers rose 6.9%.
Within these input costs, prices for nonferrous metals and cables increased 20.0% from a year earlier. Fuel and power costs rose 13.6%, while raw chemical material prices increased 12.6%.
Maham Imran, Research Associate at Foundation Securities, said simultaneous price increases across metals, energy and chemicals could complicate inflation expectations by affecting multiple industries at once.
“When several major input categories become more expensive together, companies have fewer opportunities to offset one cost against another. That can squeeze margins or push firms towards higher selling prices, particularly in sectors with energy-intensive and metal-intensive production,” she said.
The United Kingdom provides another indication of how higher industrial input costs can spread through manufacturing supply chains.
The Office for National Statistics reported that producer input prices rose 8.3% year on year in September.
Prices for metals and non-metallic mineral inputs increased 9.6%, while basic iron, steel and alloys rose 10.8%. Prices for other basic metals and casting increased 18.7%.
Factory-gate prices for basic metals, fabricated metal products, and machinery rose 6.1% year on year, indicating that input-cost pressures were filtering into manufacturers’ selling prices.
However, uneven movements among individual metals continue to blur the broader commodity outlook.
China’s latest market-price monitoring showed that electrolytic copper prices fell 0.7% in late October compared with mid-month levels, while aluminium ingot prices increased 0.9%.
These divergent movements illustrate how individual commodities can follow different price trends even within the same broader cycle of industrial cost pressures.
Imran said such volatility could make planning more difficult for manufacturers and investors, particularly when businesses needed to make procurement, inventory and pricing decisions.
“Short-term reversals do not remove the inflation risk if the average cost base remains elevated. For businesses, uncertainty itself becomes a cost because procurement, inventory and pricing decisions become harder to manage,” she said.
Consumer inflation also remains elevated in several major economies, increasing concerns about the potential transmission of industrial cost pressures to household prices.
US consumer prices were 3.7% higher year on year in September, while UK consumer inflation reached 3.5% and euro-area inflation stood at 3.8%.
Zia said policymakers needed to monitor producer-price developments alongside headline inflation to understand how commodity-price changes were affecting the broader economy.
“If commodity volatility continues feeding into intermediate goods, central banks may find that inflation remains persistent even when some energy prices stabilise. The key question is whether firms absorb these costs or pass them through.”
The latest producer-price trends suggest that global inflation risks extend beyond energy markets, as metals and other industrial inputs increasingly drive manufacturing cost pressures.
For businesses, sustained volatility could complicate investment and pricing decisions, while policymakers face the challenge of assessing whether higher production costs will eventually translate into more persistent consumer inflation.